Updated September 2026 with FLYP's current project figures.
Price against renovated comps, not against your invoices
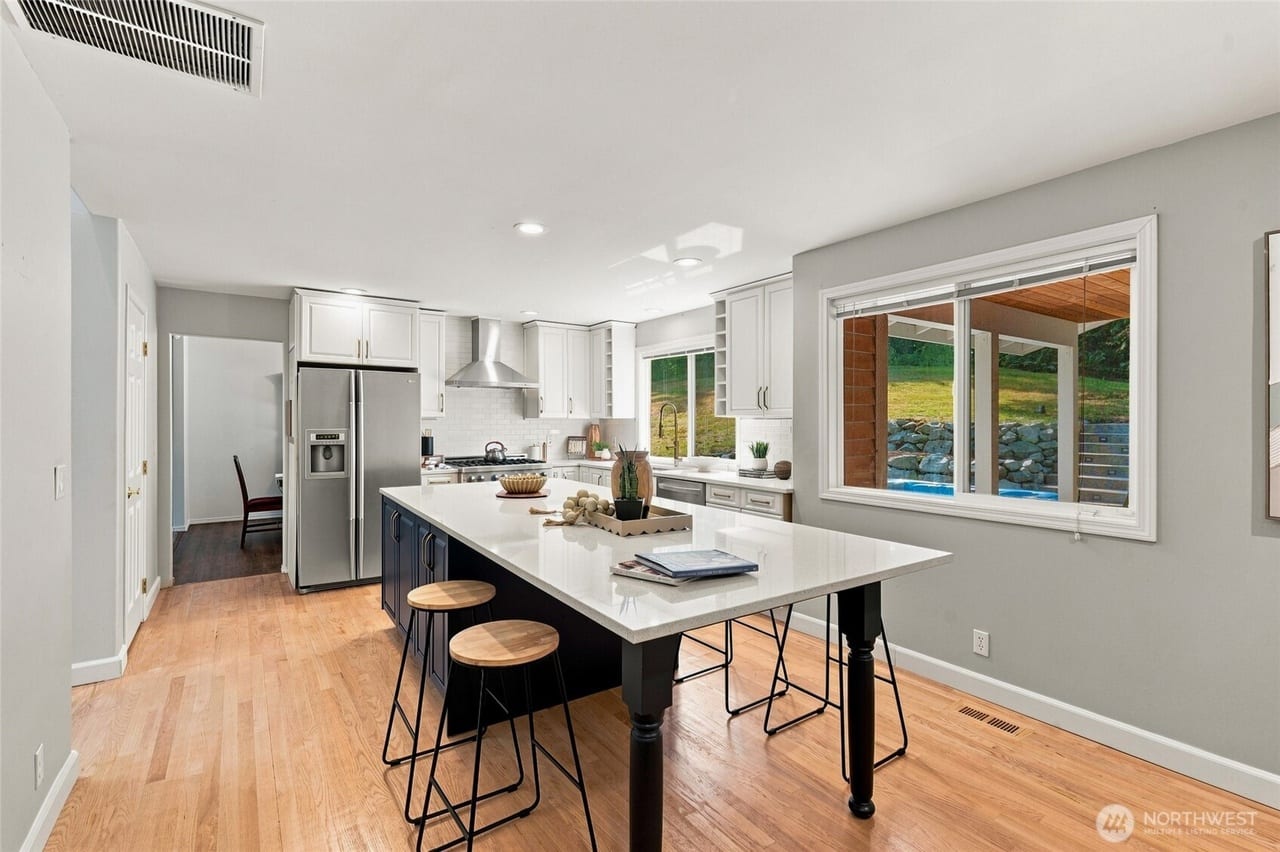
The price of a renovated home is set by what comparable renovated homes have recently closed for in your immediate area. It is not set by what you spent, and it is not your spend plus a margin you think you earned.
This is the single most expensive misunderstanding in a pre-sale renovation. A seller adds up the contract price, the sales tax, the staging, the carrying costs, the interest, the stress, and arrives at a number that feels fair. Then they ask the market to validate it. The market does not care about the arithmetic. A buyer comparing three updated houses in the same school attendance area prices yours against the other two, and an appraiser working for that buyer's lender does the same thing with closed sales.
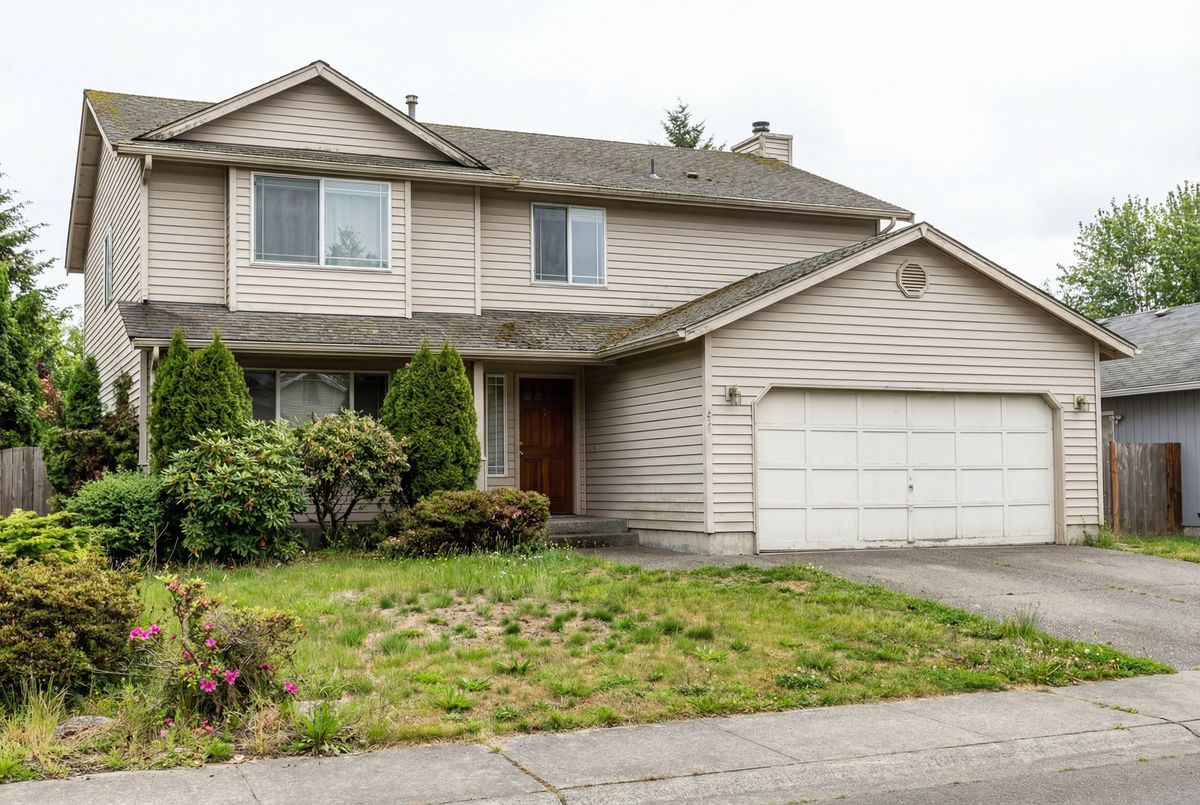
The renovation still pays. It pays by moving your home out of the "needs work" bucket, where the buyer pool is thin and discounts are deep, into the move-in-ready bucket, where the pool is widest. What it does not do is create a private price tier that only your house occupies.
The competing-inventory backdrop this spring
Pricing discipline matters more when buyers have options, and right now they have more of them. NWMLS reported that active listings across its service area ended April 2026 at 18,563, up 28.4% year over year and more than 23% above March, with 21 of 27 counties posting double-digit inventory gains. Closed sales went the other direction, down 3.7% from a year earlier, while the median sale price for homes and condos was flat year over year at $650,000.
The county spread is wide, which is why a statewide headline is not your pricing strategy. In the April report, Snohomish County inventory was up 58%, with Skagit up 44.5% and Thurston up 43.3%. A month earlier, Pierce County active listings were up 26.8% year over year with a median of $557,000, and Thurston's median sat at $535,000, equal to a year ago.
The pattern is consistent across the region: more homes for sale, slightly fewer of them closing, and prices holding rather than climbing. That is a buyer with time to compare.
Read those together and the message for a late-May listing is simple. Demand is present, buyers are looking, but they are looking at more houses than they were last spring, and sellers who start high are the ones cutting later.
How appraisers actually treat a recent renovation
An appraiser is not valuing your project. They are valuing the house as it sits, using closed sales, and then making adjustments for differences in condition, quality, size, and location. A few consequences follow.
Closed sales beat list prices. The three optimistic active listings that support your price in your head are not evidence. Only closed, verifiable sales are, and in a market where prices have flattened, a comp from five months ago may be adjusted rather than accepted at face value.
Condition adjustments are usually smaller than your spend. If the best comps are unrenovated homes on your street, the appraiser adjusts upward for your condition, but that adjustment reflects market reaction to condition, not the invoice. A large renovation does not automatically produce an equal-sized adjustment, and recovery varies by project type and market. Zonda's 2025 Cost vs. Value Report is a useful reality check on how differently projects recover cost, though its resale figures come from surveys of real estate professionals rather than from recorded sales.
Over-improvement is real. A kitchen finished two grades above everything else on the block is a lifestyle win and a valuation problem, because there are no local sales to support the premium.
Documentation that actually helps
Give the appraiser a short, factual packet at the inspection. Not a sales pitch, just verifiable facts:
- A one-page scope list of what was replaced, with completion dates
- Permit numbers for structural, electrical, plumbing and mechanical work, and the issuing city or county
- Dated before-and-after photos, especially of things now hidden behind drywall
- The signed contract scope and any signed change orders, so square footage and systems claims can be verified
- Age and type of roof, furnace, water heater, electrical panel and windows
- The contractor's Washington registration and the written workmanship warranty
- Three to five closed sales you believe are the true comps, with a sentence each on why
A packet like this rarely invents value. It routinely prevents value from being missed, which is a different and very real thing.
The over-pricing trap
Here is how a good renovation gets given back. The home lists meaningfully above what renovated comps support, because the seller is pricing the project rather than the house. Showings happen in week one, then thin out. The listing goes quiet through week three. A price cut arrives in week four, which tells every watching buyer and agent that the seller was wrong once and may be wrong again. The eventual accepted offer lands below where a correctly priced listing would have landed in its first ten days, and the seller has paid an extra month of carrying costs to get there.
In a spring where inventory is up more than 28% year over year, the penalty for that sequence is larger than it was two years ago, because your listing is not the only updated house a buyer will see this weekend. If your home already went through this cycle before the renovation, our notes on a listing that did not sell walk through the reset.
The alternative is unglamorous and effective. Price at or just under what the renovated comps support, let the finished condition do the differentiating, and give yourself the chance to be the listing buyers compete over rather than the one they use as a reference point.
If the appraisal comes in below contract
It happens, and it is not the end of the transaction. Your options, with honest trade-offs:
| Option | How it works | Trade-off |
|---|---|---|
| Buyer brings the difference in cash | Buyer covers the gap between appraised value and contract price | Only works if the buyer has reserves and the contract allows it |
| Reduce the price to the appraised value | Cleanest path to closing | You absorb the entire gap |
| Split the gap | Seller reduces, buyer adds cash | Requires a buyer who still wants the house more than the argument |
| Reconsideration of value | Lender-run review of the appraisal based on documented errors or missed comps | Takes time, and outcomes are uncertain |
| Seller credit or rate buydown instead of a price cut | Keeps the contract price, helps the buyer's payment | Does not fix a loan-to-value shortfall |
| Cancel and relist | Start over with better pricing | New days on market, new carrying costs, and no assurance of a better outcome |
On reconsideration of value, know that the process is a defined one, not a favor. In 2024, FHA, Fannie Mae and Freddie Mac all issued structured reconsideration-of-value guidance. FHA now requires lenders to establish an appeal process that includes steps for the borrower to receive a copy of the appraisal report and request an ROV when the borrower believes the report is inaccurate or deficient, and Fannie Mae asks that a borrower's request name the property, the appraiser and the unsupported, inaccurate or deficient areas of the report, with supporting comparable sales. An ROV succeeds on specifics: a missed closed sale, a wrong square footage, an ignored permitted addition. It does not succeed on disappointment. Your agent drives this with the buyer's lender, and if real money or contract rights are at stake, ask an attorney.
Where FLYP's underwriting fits, and where it does not
FLYP funds and manages pre-sale renovations that the homeowner pays for out of closing, so pricing risk is not an abstract topic for us. Before we take a project, we require a minimum 1.30x coverage ratio. That means projected net proceeds, the projected after-renovation value less selling costs and less the balance of every senior lien, divided by the maximum amount that could ever become payable to FLYP, has to be at least 1.30. It is an underwriting safety margin, not a return and not a promise about the sale, and it exists precisely because a price can miss.
Across the 12 homes that had a projected after-renovation value in our underwriting files as of September 2026, out of 16 homes underwritten in total, the projected lift over as-is value had a median of 27% and a range of 1% to 89%, and the projected dollars added had a median of $190,000 and a range of $10,000 to $500,000. Those are projections made during underwriting, not sale results, several of our files projected almost no lift at all, and no FLYP home has sold yet. A projection can be wrong. The market can move while the work is underway. A home can sell for less than projected. A homeowner can lose money or equity.
The terms are fixed and worth stating plainly: $0 upfront and $0 during the work, no monthly payments, repaid at closing as the fixed contract price on the signed estimate plus Washington sales tax, any change orders you signed, and the county recording fee. No interest during the renovation and none for six months after the work is finished, then 1.5% per month on the balance. Ten months after completion the balance is due directly, whether or not the home has sold. The balance is secured by a deed of trust recorded against the property. The plain-language summary is at how the process works, and the program details are on the pay-at-closing renovation page.
FLYP is the wrong tool for some sellers. If the plan only works when the home sells at the top of the renovated range, the margin for error is too thin. If you are staying put, a conventional paid remodel is the honest structure. And if speed and certainty matter more than net proceeds, we can help arrange an as-is cash offer instead, with terms depending on the property.
The bottom line
Your price comes from closed sales of comparable renovated homes, not from what the project cost. With active listings up sharply across the region, a first number set above what those comps support buys you three quiet weeks and a price cut that tells every watching buyer you were wrong once. Price at or just under the renovated comps, hand the appraiser a factual packet of scope, permits, dates and photos, and know your options in advance if the appraisal lands low.
If you are weighing a pre-sale renovation and want the comp math checked before you commit, start here and we will look at your actual block.